
Why This Matters to Distributors: Grainger reported double-digit growth in product volume in its North American business, indicating that higher sales reflected more customer purchases as well as price increases. Growth at MonotaRO and Zoro also strengthened, while freight costs continued to pressure profitability in North America.
Grainger raised its full-year sales and earnings forecast Nov. 4 after third-quarter sales increased 11.3%, supported by stronger customer demand, higher prices, and growth across its North American and online distribution businesses.
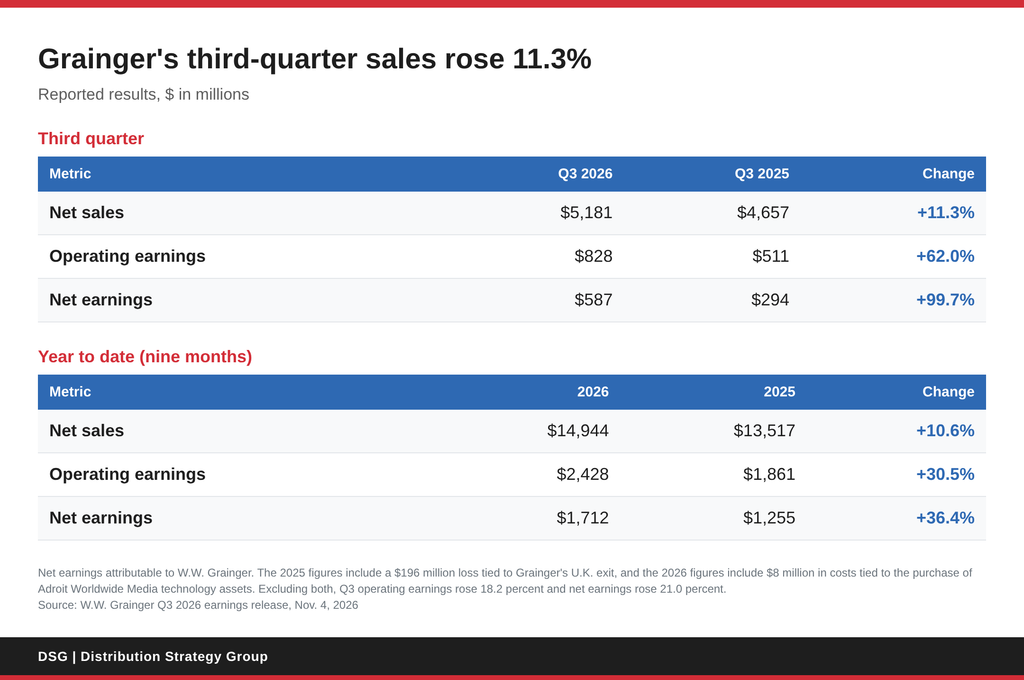
The distributor of maintenance, repair, and operating supplies reported sales of $5.18 billion for the quarter ending Sept. 30, up from $4.66 billion a year earlier. Net earnings nearly doubled to $587 million from $294 million, an increase of 99.7%.
The sharp earnings increase partly reflected a $196 million loss recorded a year earlier for leaving the United Kingdom. Excluding that loss and acquisition-related costs in the latest quarter, the company said adjusted net earnings increased 21% to $593 million from $490 million.
“As customers continue to turn to us for the products and solutions they need, both our High-Touch Solutions and Endless Assortment segments delivered impressive growth,” CEO D.G. Macpherson said
For the first nine months of 2026, sales increased 10.6% to $14.94 billion from $13.52 billion. Net earnings rose 36.4% to $1.71 billion from $1.26 billion. That earnings comparison also includes the effect of last year’s U.K. exit loss.
Grainger serves more than 4.6 million customers worldwide, with operations primarily in North America and Japan.
Sales in Grainger’s High-Touch Solutions North America business increased 13.8% from the third quarter of 2025. The company attributed the increase to double-digit growth in product volume and higher selling prices as it passed along cost increases.
The volume growth shows that the sales increase went beyond inflation: Customers bought more products, in addition to paying higher prices. Grainger did not provide a more specific volume growth rate or separate the sales contribution from pricing in the release.
The business retained 40.8 cents of each sales dollar after paying for products and related costs, down from 41.1 cents a year earlier. Grainger attributed the decline to higher freight expenses and changes in the mix of products or customers served.
Despite that pressure, the company said rising sales helped improve companywide operating profitability by spreading expenses across a larger sales base.
Sales in Endless Assortment, which includes MonotaRO and Zoro, increased 11.9%. After removing the effects of currency changes and the closure of Zoro U.K., sales increased 19.3%.
Grainger attributed the increase to robust performance at both MonotaRO and Zoro. The release did not provide separate sales growth rates for the two businesses.
The online businesses also improved the amount they retained from sales after product and related costs. That share increased by 0.9 percentage points from a year earlier, with improvements at both companies.
Across Grainger, sales increased 14.9% after removing currency effects and excluding the former U.K. businesses from the comparison. Both third quarters had 64 selling days, so the number of business days did not affect the growth rate.
Grainger sold its Cromwell business and closed Zoro U.K. in the fourth quarter of 2025. Those operations were included in the third quarter of last year, affecting comparisons with the latest results.
Grainger’s operating earnings (profit before interest and income taxes) increased 62% to $828 million from $511 million.
After excluding the U.K. exit loss in 2025 and $8 million in costs associated with acquiring technology assets in 2026, operating earnings increased 18.2% to $836 million from $707 million.
Grainger said stronger business performance, fewer shares outstanding and a lower tax rate contributed to the per-share increase. Its reported tax rate fell to 24.3% from 34.7%; after accounting for the prior-year U.K. loss, the comparison was 24.3% against 24.8%.
The release disclosed costs associated with acquiring technology assets from Adroit Worldwide Media Inc. Grainger recorded $8 million in expenses related to the transaction during the quarter.
Grainger generated $661 million in cash from its operations during the quarter, up from $597 million a year earlier. It spent $115 million on property, equipment, and other long-term investments, leaving $546 million after those expenditures.
For the first nine months, cash generated by operations increased to $1.84 billion from $1.62 billion. Spending on property, equipment and other long-term investments totaled $396 million, compared with $558 million a year earlier.
Grainger now expects full-year sales of $19.8 billion to $20 billion, up from its previous forecast of $19.4 billion to $19.7 billion. The revised range represents growth of 10.1% to 11.6% over 2025.
Excluding currency changes and the effect of businesses it sold or closed, the company expects sales growth of 13% to 14.5%, compared with its previous forecast of 11.5% to 13%.
The company increased its profitability expectations for Endless Assortment and narrowed its expected range for the North American business.
Do not miss any content from Distribution Strategy Group. Join our list.
Share this article:
