Why This Matters to Distributors: Pool Corp. grew sales while reducing inventory, supported by higher prices, stronger maintenance activity, and improving building materials sales. Rising freight and operating expenses nevertheless reduced earnings, illustrating the pressure on distributors to control costs as revenue improves.
Pool Corp.’s sales growth accelerated in the third quarter as maintenance activity and building materials sales strengthened, but higher freight and employee-related costs pushed profit below year-earlier levels.
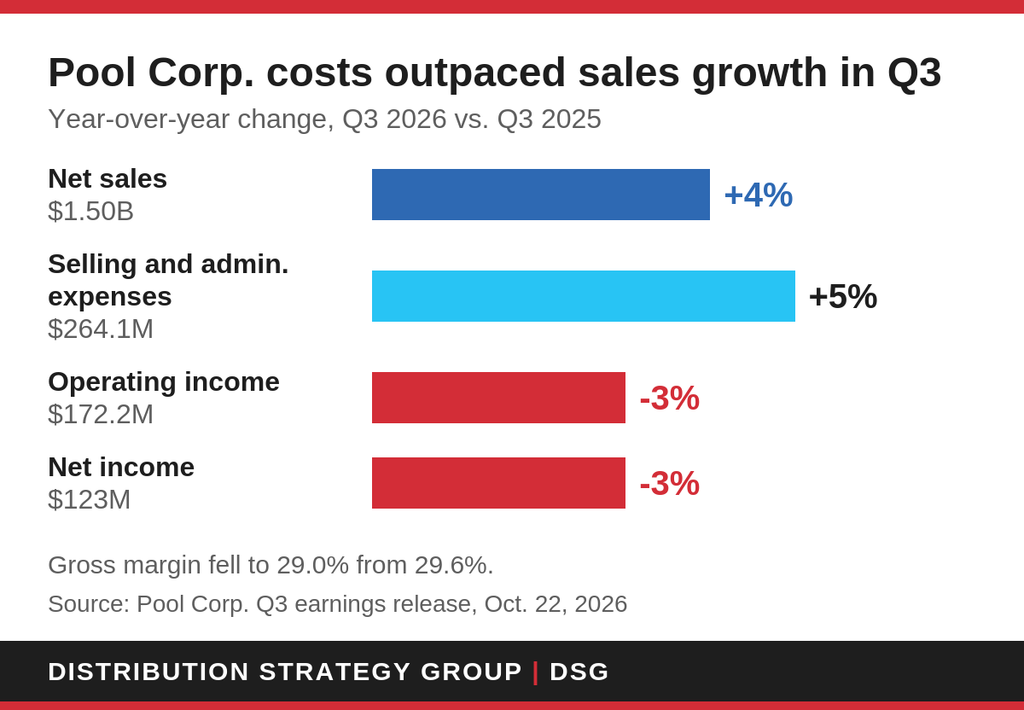
The Covington, Louisiana-based distributor of swimming pool and backyard products reported Oct. 22 that sales rose 4% to $1.50 billion in the quarter ended Sept. 30, up from $1.45 billion a year earlier. Net income fell 3% to $123 million from $127 million.
The sales increase improved on the second quarter’s 2% growth. Higher prices contributed 3% to third-quarter growth, with maintenance activity and building materials providing additional gains.
For the first nine months of 2026, sales increased 4% to $4.47 billion from $4.31 billion. Net income declined 3% to $364.4 million from $374.8 million.
President and CEO John Watwood said the company increased sales as it moved through the end of its peak selling season while continuing to reduce inventory. Products held in inventory totaled $1.19 billion on Sept. 30, down 3%, or $38.6 million, from a year earlier.
The improvement in sales did not fully offset rising expenses. Higher inbound freight costs and changes in the mix of customers reduced the portion of each sales dollar remaining after product costs to 29 cents, down from 29.6 cents a year earlier. The comparison also reflected benefits from midseason price increases in 2025.
Selling and administrative expenses rose 5% to $264.1 million from $251.2 million, outpacing sales growth. Pool Corp. attributed the increase to higher performance-based compensation, employee insurance costs and outside fees associated with strategic initiatives.
As a result, operating income fell 3% to $172.2 million from $178 million. For the first nine months, operating income declined to $522.5 million from $528.2 million.
Year-to-date operating expenses included $8.3 million related to the chief executive transition, consisting of $6.3 million associated with previously granted stock awards and $2 million in cash costs. Excluding those expenses, operating costs increased 4%, and operating income was unchanged from a year earlier.
Pool Corp. generated $419.8 million in cash from operations during the first nine months, up 47% from $285.7 million. Spending on property and equipment totaled $49.8 million, compared with $48.1 million a year earlier.
The company finished September with 454 sales centers across North America, Europe, and Australia, compared with 456 at the beginning of the year. It opened two locations and consolidated four during the nine-month period.
Sales centers excluded from the company’s comparison of established operations contributed less than 1% to the change in reported sales. Those exclusions cover certain acquired, newly opened, closed, or consolidated locations, indicating that growth came from the existing business.
The company distributes more than 200,000 products to 125,000 wholesale customers and describes itself as the world’s largest wholesale distributor of swimming pool and related backyard products.
Do not miss any content from Distribution Strategy Group. Join our list.
Share this article:
