

Why This Matters: HVACR distributor sales posted their strongest monthly increase of 2026 in July, but HARDI said weather played a significant role in the gain and underlying end-market demand remains subdued.
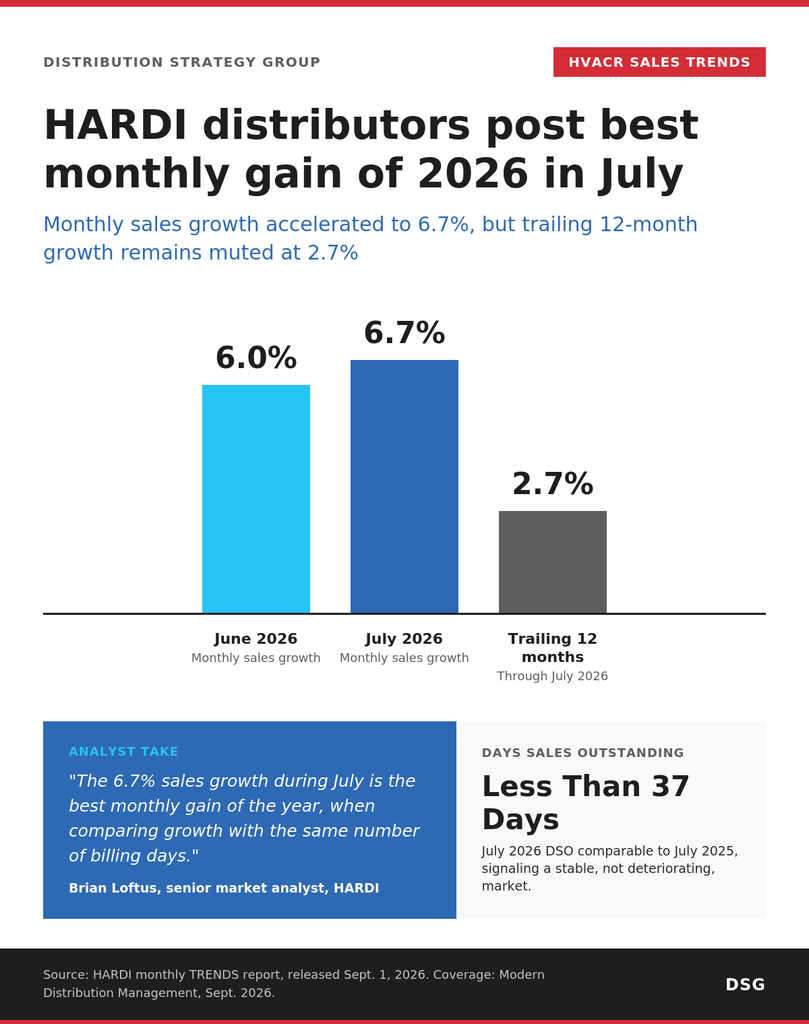
Heating, air-conditioning and refrigeration distributor sales increased 6.7% in July from a year earlier, the strongest monthly gain of 2026 on a comparable billing-day basis, according to the latest industry data.
Heating, Air-conditioning & Refrigeration Distributors International, or HARDI, said the 12-month sales growth rate through July was 2.7%, well below July’s year-over-year increase.
The divergence underscores an uneven market in which weather provided a significant boost to July sales, but broader demand has yet to show a sustained acceleration.
“The 6.7% sales growth during July is the best monthly gain of the year, when comparing growth with the same number of billing days,” HARDI Senior Market Analyst Brian Loftus said. “The good report is not telling us much about the market. The strongest regions had the biggest cooling degree day increases, and the weakest regions had big cooling degree day declines.”
Cooling degree days measure how much and for how long outside temperatures exceed a baseline temperature and are an indicator of demand for air conditioning. Higher cooling degree days can drive additional demand for HVAC equipment, replacement parts and service.
The July results therefore provide a stronger reading on distributor sales but not necessarily evidence that the broader HVACR market has turned a corner.
HARDI said end-market demand has been subdued for more than two years, while weakness in housing and pressure on consumers continue to weigh on the industry.
“The housing market has been depressed, like consumer sentiment which is under pressure from stubborn inflation,” Loftus said. “The market is due for a change. We would have more confidence that signs of improvement could endure if inflation and interest rates would subside.”
Distributor customer payment patterns, however, have remained stable.
Days sales outstanding were less than 37 days in July, roughly unchanged from July 2025. The metric measures how long it takes distributors to collect payment from customers after a sale and can provide an indication of changes in customer financial conditions.
“End market demand has been subdued for more than two years,” Loftus said. “The steady DSO indicates the market is not deteriorating.”
The combination of stronger sales and stable customer payment patterns provides some positive signals for distributors entering the second half of the year. But the gap between July’s 6.7% increase and the trailing 12-month growth rate of 2.7%, coupled with the significant influence of regional weather patterns, points to a market that remains uneven.
HARDI represents more than 570 distributor members with more than 5,000 branch locations, along with nearly 600 suppliers, manufacturers’ representatives and service vendors across North American and Latin American HVACR markets.
HARDI’s monthly TRENDS report is based on voluntary sales data submitted by participating distributors.
Do not miss any content from Distribution Strategy Group. Join our list.
Share this article:
