

Why This Matters to Distributors: Buyers continue investing in technical expertise, specialized services, and established customer relationships. Private equity-backed distributors are expanding through acquisitions, but the third-quarter recovery has not erased an earlier slowdown in deal activity.
Distribution acquisition activity increased in the third quarter of 2026, narrowing a year-to-date decline as corporate buyers and private equity investors pursued businesses with specialized capabilities and access to new markets.
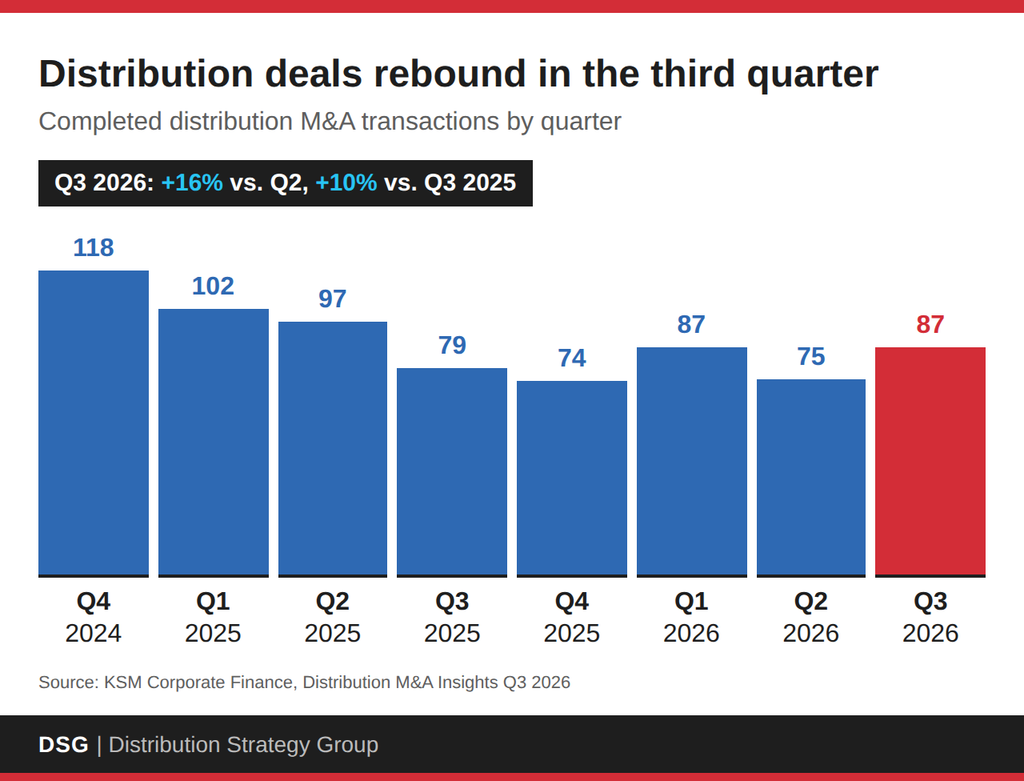
KSM Corporate Finance recorded 87 completed distribution transactions during July through September, up 16% from 75 in the second quarter and 10.1% from 79 a year earlier. Industrial distribution led to the recovery, while building products activity softened from the preceding quarter.
The improvement brought the nine-month total to 249 transactions, down 10.4% from 278 during the same period in 2025, according to calculations using KSM’s quarterly figures.
The year began with 87 transactions in the first quarter, down 14.7% from 102 a year earlier. Second-quarter activity fell 22.7%, to 75 transactions from 97. Those declines left first-half activity down 18.6%, making the third quarter increase a partial recovery rather than a return to the previous year’s pace.
The latest quarterly total matched the first quarter of 2026 but remained below 97 transactions in the second quarter of 2025 and 118 in the fourth quarter of 2024.
Corporate Buyers Lead as Private Equity Activity Increases
Corporate acquirers remained the largest source of distribution transactions, according to KSM. Their acquisition priorities included expanding market coverage, adding capabilities and improving efficiency across combined operations.
Private equity and transactions KSM classifies as hybrid, however, drove the quarterly increase. Hybrid transactions accounted for 26.4% of third-quarter activity, or approximately 23 of the 87 deals.
KSM said acquisitions added to existing holdings remained a priority for private equity investors. That approach allows an established distribution business to expand its geographic reach, product assortment, or services through smaller purchases.
The firm described capital as available but buyers as selective. Its outlook favored distributors with technical expertise, specialized services, and exposure to attractive customer markets, while emphasizing strategic fit and confidence that transactions could close.
The findings distinguish the buyers responsible for the largest share of transactions from those driving the latest increase. Corporate buyers remained the most active overall, while private equity and hybrid transactions supplied quarterly momentum.
Established Platforms Continue Adding Businesses
KSM highlights five private equity-backed acquisition platforms: RelaDyne, White Cap, Compactor Rentals of America, GME Supply and SouthernCarlson. Its selected transactions illustrate their activity but do not constitute complete year-to-date totals or an industry ranking.
RelaDyne, which KSM identifies as owned by American Industrial Partners, has three 2026 acquisitions listed: Chart Distribution Group in St. Louis in May, OilRed in Itagui, Colombia, in July and Rossee Oil in Eatonton, Georgia, in September. The purchases illustrate expansion across domestic and international markets.
White Cap, identified as backed by Clayton, Dubilier & Rice, also has three acquisitions listed for 2026. It added Concrete Systems in Newark, New Jersey, in May; Gierke-Robinson in Davenport, Iowa, in August; and Ace Contractors Supply in La Grange, Texas, in September.
Compactor Rentals of America, backed by Kinderhook Industries, has three listed purchases concentrated in the second quarter. It acquired Tower Compactor Rentals in Scottsdale, Arizona, in April, followed by Diamond Compactor Rentals in Rantoul, Illinois, and Reddy Equipment in Solon, Ohio, in June.
The report also identifies acquisition activity at GME Supply, backed by Incline Equity Partners, and SouthernCarlson, backed by Truelink Capital. GME Supply added ASK Tower Supply in Albuquerque, New Mexico, in May. SouthernCarlson added Greenwald Supply Direct in Hyattsville, Maryland, in March and W Construction Supply in North Canton, Ohio, in May.
KSM includes older purchases for both companies, which should not be counted as 2026 transactions. Among the selected deals shown, RelaDyne, White Cap and Compactor Rentals of America each have three dated in 2026, SouthernCarlson has two and GME Supply has one.
Investors Buy New Platforms and Sell Existing Holdings
Alongside those acquisitions, investors continued buying distribution businesses that could support further expansion.
Incline Equity Partners announced its investment in The Conrad Company on Sept. 29. The York, Pennsylvania-based business distributes fluid power, motion control, automation, and related industrial products, supported by technical service and repair capabilities. Incline said it would pursue expansion into adjacent offerings through internal growth and acquisitions.
KSM also highlights Atlantic Street Capital’s September investment in GLP Canada and BPOC’s August investment in Master Medical Equipment. GLP supplies heating, ventilation and air conditioning equipment, components, and engineered systems. BPOC’s investment included sister company ReNew Biomedical, combining medical equipment distribution with repair and maintenance services.
Other investors sold established holdings. OmniCable announced Aug. 27 that it had completed its acquisition of Kingwire by Kinderhook Industries. Kingwire operates eight warehouses totaling more than 625,000 square feet and supplies wire and cable to electrical distributors.
OmniCable said the acquisition strengthens its distributor stock programs and aluminum product offerings while providing access to the utility channel. Financial terms were not disclosed.
KSM’s selected exits also include Tinicum’s acquisition of GracoRoberts from CM Equity Partners in July and Clarendon Capital’s acquisition of O’Donnell Metal Deck from Slate Capital Group that month. The report does not provide purchase prices for those transactions.
Larger Deals Add Technical Expertise and Customer Channels
Several larger transactions show buyers committing substantial capital to capabilities they can offer across broader customer networks.
Ferguson completed its acquisition of FloWorks from Wynnchurch Capital on Aug. 31, following a July announcement valuing the business at approximately $1.6 billion, including debt.
FloWorks generated approximately $1 billion in 2025 revenue and operated more than 60 locations in the United States and Canada. Its offerings include technical valves, automation, specialty flow control products, and service and repair capabilities.
Ferguson identified data centers, semiconductor manufacturing, power generation and pharmaceuticals among the customer markets the acquisition would help it serve. The company projected approximately $45 million in benefits from combining the businesses.
Rexel’s planned acquisition of GCG reflects a similar emphasis on specialized infrastructure products and services. Announced Sept. 25, the transaction values GCG at approximately $1.4 billion, including debt. The companies expected to close by year-end, making a third-quarter announcement rather than a completed third-quarter deal.
GCG operates 16 locations with approximately 950 employees and was expected to generate more than $1.1 billion in 2026 revenue. Its capabilities include engineering, custom assembly, product modification, kitting, and testing.
Rexel said more than 75% of GCG’s revenue incorporates products or services with additional technical content. More than 60% comes from markets it identifies as high growth, including data centers, power infrastructure, grid modernization, and communications.
Hillman Solutions took a different route into industrial distribution, completing its acquisition of Kanebridge on Aug. 28 for approximately $315 million, subject to customary adjustments. The completion date appears in Hillman’s securities filing; KSM’s discussion uses the Sept. 3 announcement date.
Kanebridge supplies more than 44,000 commercial and military-grade fastener products to distributors across the United States and Canada. Hillman said the acquisition establishes its first U.S. industrial fastener master distribution business and expands its potential industrial market to approximately $3 billion.
Smaller Acquisitions Establish New Positions
KSM also spotlights DXP Enterprises’ acquisition of Mequipco, a Calgary, Alberta-based manufacturer’s representative serving municipal and industrial water and wastewater customers.
Announced Aug. 4, the transaction gave DXP Water an initial operating base in Canada, with three locations serving Western Canada. KSM identifies it as DXP’s fifth acquisition in 2026.
Mequipco generated approximately 9.9 million Canadian dollars in sales during the 12 months ended June 30. DXP said it financed the purchase with cash and company stock but did not disclose the purchase price in the announcement.
FreightCar America’s July acquisition of Southern Parts & Equipment similarly expanded an aftermarket business. The Monroe, Georgia-based distributor supplies new, used, and reconditioned railcar parts and equipment to repair shops, railroads, private railcar owners, and industrial customers.
Southern Parts & Equipment also provides consulting, inspections, and project services. KSM identifies the purchase as FreightCar America’s second railcar aftermarket acquisition within a year but does not provide a transaction price.
FactSet Finds Distribution Gaining Against a Mixed Market
FactSet’s separate review counted 144 distribution services deal announcements during the three months through September, up 19% from 121 a year earlier. Its announcement-based figures cover a different transaction population from KSM’s completed-deal count and cannot be combined with KSM’s totals.
Distribution was among seven of FactSet’s 21 sectors with increased activity, while 13 declined. Producer manufacturing announcements rose 13.5%, to 210 from 185; retail trade increased 27.6%, to 111 from 87; and electronic technology climbed 27.3%, to 98 from 77.
Several larger sectors weakened. Finance announcements fell 27.1%, to 726 from 996, while technology services declined 9.5%, to 799 from 883. Consumer services fell 22%, to 220 from 282.
The monthly figures also showed softer conditions: total U.S. announcements declined 1.7% in September from August, while acquisition spending dropped 27.5%. FactSet’s public review does not provide a comparable distribution-specific spending total.
Recovery Varies Across Distribution Markets
KSM’s public market data reinforces the differences across distribution segments. Technology distribution shares gained approximately 10% during the third quarter, while healthcare and industrial shares each rose by about 2%. Food and beverage shares declined approximately 2%.
Automotive and building products recorded sharper declines of 14% and 17%, respectively, extending their one-year losses to approximately 25% and 31%. Those figures describe stock performance, not acquisition counts or business sale prices.
Taken together, the research and transactions point to a selective recovery. Buyers are pursuing technical capabilities, specialized customer relationships, and established routes into new markets, while private equity-backed platforms continue adding businesses.
The third-quarter increase nevertheless leaves deal activity below the first nine months of 2025. Neither report establishes an industrywide increase in acquisition prices or total investment dollars.
Do not miss any content from Distribution Strategy Group. Join our list.
Share this article:
